How to add quadratic constraint in conditional indicator constraints
AnsweredHi Gurobi Community,
I am trying to add a conditional indicator constraint using addGenConstrIndicator . E.g. a simple example like this:
import gurobipy as gp
m = gp.Model()
x = m.addVar(vtype=GRB.BINARY, name="x")
y = m.addVar(lb=-10, ub=10, name="y")
m.addGenConstrIndicator(x, True, y <= 4)
However, unfortunately in my case the constraint is not linear and it is quadratic but adding quadratic constraints like:
m.addGenConstrIndicator(x, True, y**2 <= 4)
seems to be not acceptable. I want to know is there another way or any sort of hack or workaround to this that I can add my quadratic constraint in the same way?
My real constraint is the following:
i = model.addVars(gurobi_variants, name='i', vtype=GRB.BINARY)
n = model.addVars(gurobi_replicas, name='n', vtype=GRB.INTEGER, lb=1, ub=scaling_cap)
b = model.addVars(gurobi_batches, name='b', vtype=GRB.INTEGER, lb=1, ub=batching_cap)

for stage in stages:
     for variant in stages_variants[stage]:
          model.addConstr((i[stage, variant] == 1) >> ((n[stage] * b[stage] - arrival_rate * func_l(b[stage], latency_parameters[stage][variant])) >= 0), f'throughput-{stage}')
all the other none Gurobi parameters like `stage` are constants in the above example. The terms:
n[stage] * b[stage]
is making it quadratic.
-
Official comment

-
Gurobi Staff
This post is more than two years old. Some information may not be up to date. For current information, please check the Gurobi Documentation or Knowledge Base. If you need more help, please create a new post in the community forum, or try Gurobot, our chatbot interface offering instant, expert-level support. -
-

-
Consider your simplified version of modeling \( x = 1 \implies y^2 \leq 4 \). Let \( \ell \) and \( u \) be \(y\)'s lower and upper bounds, respectively. We can model this implication with the constraint
$$\begin{align*}y^2 &\leq 4 + (M-4)(1-x),\end{align*}$$
where \( M = \max\{\ell^2, u^2\} \). In this case, \( M = 100 \).
If \( x = 1 \), then the constraint becomes \( y^2 \leq 4 \), as desired. If \( x = 0 \), then the constraint enforces \( y^2 \leq 100 \), which is redundant with \( y \)'s bounds.
0 -
-

Hi Eli,
Thank you for your answer! how about the situation where we have two distinct variables in our formulation that are making it quadratic e.g. $z.y <= 4$ then the only modification to your solution would be to change the $M$ to $M=max{l_{z} * l_{y}, u_{z} * u_{y}}$ and the formulation to $z.y <= 4 + (M-4)(1-x)$ where $l_{z}, l_{y}$ and ${u_z}$ and $u_y$ are the lower and upper bound of $z$ and $y$ respectively, correct?In a more complicated scenario I have ($x$ is the indicator variable):
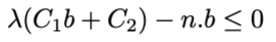
Where $n$ and $b$ are variables and the rest are constants. Can I do the same in the following format?
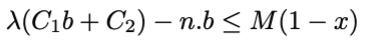
and set the $M$ to the following (considering all the variables and constants values are positive):
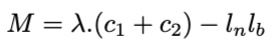
where $l_b$ and $l_n$ are lower bounds of variable $n$ and $b$, does such an extension from your solution make sense to you?
And is there any caveat to setting the value of $M$ to an extremely large number instead of explicitly computing $M$ with lower and upper bounds of variables? Will that have any effect on the performance of the optimizer?
Thanks!0 -
-
-
For the case of multiplying two distinct variables together, you should set
$$\begin{align} M &:= \max\{\ell_y \ell_z, \ell_y u_z, u_y \ell_z, u_y u_z\}.\end{align}$$
For example, for \( y \in [-2, -1] \) and \( z \in [1, 2] \), the maximum attainable value of \( yz \) is \( u_y \ell_z = -1 \).
In your more complicated scenario, it looks like you want to enforce
$$\begin{align} yz - \lambda (c_1 y + c_2) &\geq 0 \end{align}$$
when \( x = 1 \). Is that right? If so, we should derive a valid lower bound for \( y z - \lambda (c_1 y + c_2) \). We can break this into two parts:
- A lower bound for \( y z \) is \( m_1 := \min\{\ell_y \ell_z, \ell_y u_z, u_y \ell_z, u_y u_z\} \)
- A lower bound for \( - \lambda (c_1 y + c_2) \) is \( m_2 := - \max\{\lambda c_1 \ell_y, \lambda c_1 u_y \} - \lambda c_2 \).
Putting those two together, we have the constraint
$$\begin{align} y z - \lambda (c_1 y + c_2) &\geq (m_1 + m_2)(1 - x). \end{align}$$
You should not pick an arbitrary large value for \( M \). Not only can this cause numerical trouble for the model, but it often results in a weaker root relaxation, which can cause the model to take much longer to solve. A good rule of thumb is: your big-M values should be derived from the problem data.
0 -
-
Thanks Eli! It was very helpful!
0 -
Post is closed for comments.
Comments
5 comments