TypeError: 1.0 + 0.0007 <gurobi.Var *Awaiting Model Update*> is not a variable
AnsweredI want to construct the following constraint:
b_n<=(w_nWtlog2(1+c/w_n))/D_n, where b_n and w_n are decision variables, other notations, such as W, t, are constant.
Considering that the above constraint has an item 1/w_n, we firstly introduce an auxiliary variable z_n, and add a constraint z_n * w_n = 1. Specifically,
# define the decision variable w_n
w = []
for i in range(N):
    name = 'w_' + str(i)
    x = model.addVar(0.1, 1, vtype=GRB.CONTINUOUS, name=name)
    w.append(x)
# define an auxiliary variable z_n
z = []
for i in range(N):
    name = 'z_' + str(i)
    x = model.addVar(1, 10, vtype=GRB.CONTINUOUS, name=name)
    z.append(x)
# add the constraint z_n * w_n = 1, in order to instead 1/w_n with z_n
for i in range(N):
    name = 'c1_' + str(i)
    model.addConstr(z[i] * w[i] == 1, name=name)
In addition, we introduct the variable y_n in order to construct the logarithmic function:
y = []
for i in range(N):
    name = 'y_' + str(i)
    x = model.addVar(vtype=GRB.CONTINUOUS, name=name)
    y.append(x)
# construct the constraint b_n<=(w_nWtlog2(1+c/w_n))/D_n
for i in range(N):
    temp = model.addGenConstrLogA(1 + c * z[i], y[i], 2)
    R = w[i] * W * t * y[i]
    x = R/D[i]
    name = 'c2_' + str(i)
    model.addConstr(b[i] <= x, name=name)
However, the result shows the error as follows:

Great thanks for all recommendations.
-
Official comment

-
Gurobi Staff
This post is more than two years old. Some information may not be up to date. For current information, please check the Gurobi Documentation or Knowledge Base. If you need more help, please create a new post in the community forum, or try Gurobot, our chatbot interface offering instant, expert-level support. -
-

-
Hi,
A general constraint of type LogA is in the form (Var, Var, a) where Var is a Gurobi variable object and not a Gurobi Linear Expression (LinExpr).
To implement the expression \(\log_2(1+\frac{c}{w_n})\), you need to define three auxiliary variables to represent \(z = \frac{1}{w_n}\), \(v = 1+ cz\), and then \(y=\log_2(v)\).
w = m.addVars(N, lb=0.1, ub=1, name="w")
z = m.addVars(N, name="z")
v = m.addVars(N, name="v")
y = m.addVars(N, name="y")

m.addConstrs((z[i] * w[i] == 1 for i in range(N)), name="c_bilinear")
m.addConstrs((v[i] == 1 + c * z[i] for i in range(N)), name="c_linexpr")
for i in range(N):
    m.addGenConstrLogA(v[i], y[i], 2, name="c_log")
Best regards,Maliheh0 -
-

Hi Maliheh,
your comment helps me a lot, thank you very much!
However, I have a new problem.
The problem can be modeled as follows:

For the problem, only b_n and w_n are decision variables, other notations, such as Q_n, W_n, are constants. We have proven that the objective function and all constraints are convex.
The values of these constants are as follows:
Q = [4200, 3000, 600, 5400, 1700] # each item can be denoted as Q_n
H = [300, 1500, 300, 800, 1100] # each item can be denoted as H_n
M = [200, 300, 120, 300, 200]   # each item can be denoted as M_n
M_e = [100, 50, 70, 260, 80]    # each item can be denoted as M^e_n
M_l = [100, 250, 50, 40, 120]   # each item can be denoted as M^l_n
F_l = [5.5, 3, 7, 8, 10]        # each item can be denoted as F^l_n
D = [10, 15, 20, 25, 30]        # each item can be denoted as D_n
W = 10000
p = [7, 5, 7.5, 6, 8]          # each item can be denoted as p_n
h = [1, 1, 1, 1, 1]           # each item can be denoted as h_n
N_0 = 1
Moreover, the corresponding code is:
# define the decision variable b_n, which is the integer variable
b = W_LP.addVars(N, lb=0, ub=GRB.INFINITY, vtype=GRB.INTEGER, name="b")

# define the decision variable w_n
w = W_LP.addVars(N, lb=0.1, ub=1, vtype=GRB.CONTINUOUS, name="w")

# define the auxiliary variable z_n, so as to add the constraint z_n*w_n=1 and instead 1/w_n with z_n
z = W_LP.addVars(N, lb=1, ub=10, vtype=GRB.CONTINUOUS, name="z")

# define the auxiliary variable v_n, which can be used instead of 1+(p_n*h_n/W*N_0)/w_n in log2(1+(p_n*h_n/W*N_0)/w_n)
v = W_LP.addVars(N, name="v")

# define the auxiliary variable y_n
y = W_LP.addVars(N, name="y")

# define the auxiliary variable tmp_n
tmp = W_LP.addVars(N, name="tmp")

# construct the objective function
obj = LinExpr(0)
for i in range(N):
    a = -Q[i] * M[i] + H[i] * M_e[i]
    obj.addTerms(a, b[i])
W_LP.setObjective(obj, GRB.MINIMIZE)

# add the constraint the sum of w_n is 1
constr_1 = LinExpr(0)
for i in range(N):
    constr_1.addTerms(1, w[i])
W_LP.addConstr(constr_1 == 1, name="w1")

# add the constraint z_n*w_n=1
W_LP.addConstrs((z[i] * w[i] == 1 for i in range(N)), name="c2_linear")

# add the constraint v_n=1+(p_n*h_n/W*N_0)/w_n
W_LP.addConstrs((v[i] == 1 + (p[i] * h[i] * z[i])/(W * N_0) for i in range(N)), name="c_linexpr")

# log2(1+(p_n*h_n/W*N_0)/w_n)
for i in range(N):
    W_LP.addGenConstrLogA(v[i], y[i], 2, name="c_log")

# b_n=min{F^l_n/M^l_n, (w_n*W*log2(1+(p_n*h_n/W*N_0)/w_n))/D_n},where the two items in min{} must be rounded down
for i in range(N):
    name = 'b_min' + str(i)
    W_LP.addConstr(tmp[i] == W_LP.addGenConstrMin(F_l[i]/M_l[i], (y[i]*w[i]*W)/D[i]), name=name)
W_LP.addConstrs((b[i] == int(tmp[i]) for i in range(N)), name="b2_min")

W_LP.optimize()

print("Obj: ", W_LP.objVal)
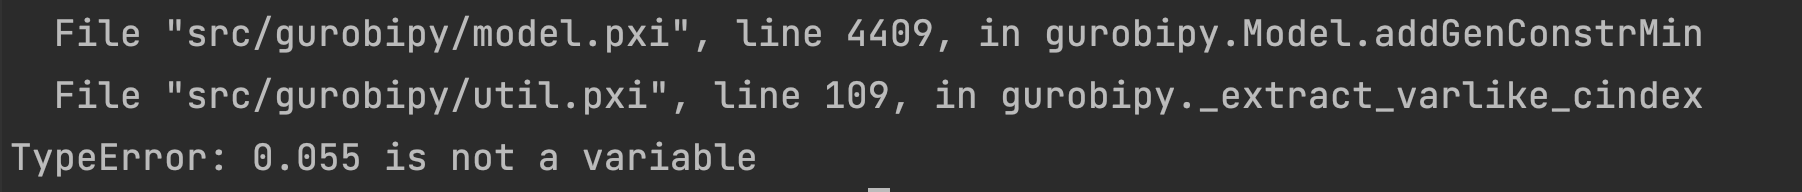
the bug shows that
Great thanks for your help!
Huan
0 -
-
-
Hi,
It seems that you are interested in modeling the constraint below:
\[b_n = \min \Big\{ \big\lfloor \frac{F^l_n}{M^l_n} \big\rfloor, \big\lfloor \frac{w_n W \log_2(1 + \frac{p_nh_n}{w_nWN_0})}{D_n} \big\rfloor \Big \}\]
- You have already defined the auxiliary variables \(y\) to represent \(\log_2(1 + \frac{p_nh_n}{w_nWN_0})\).
- Please note that the Python int() function can only be used on real numbers not on Gurobi expression objects.
- The expression \(\frac{w_n W y_n}{D_n}\) is a Gurobi QuadExpr() object. To model \(\lfloor \frac{w_n W y_n}{D_n} \rfloor\), you would need to define new auxiliary variables \(u\).
- See the code snippet below on how to implement this:
- The signature for the minimum general constraint is Model.addGenConstrMin(resvar, vars, constant, name)
u = W_LP.addVars(N, vtype=gp.GRB.INTEGER, name="u")
# Model u_i to represent the greatest integer less than y[i] * w[i] * W / D[i]
W_LP.addConstrs((u[i] <= y[i] * w[i] * W / D[i] for i in range(N)))
W_LP.addConstrs((u[i] >= y[i] * w[i] * W / D[i] - 1 for i in range(N)))

# Model b = min(int(F^l_n/M^l_n), u)
for i in range(N):
    W_LP.addGenConstrMin(b[i], [u[i]], int(F_l[i] / M_l[i]), name="b_min")
Please also note that your model is non-convex because of the following two constraints \(z_i w_i = 1\) and \(u_i \geq \frac{W}{D_i} y_i w_i - 1\). You would need to set the parameter NonConvex to 2.
Best regards,
Maliheh
0 -
-
Your reply helps me a lot, thank you very much!!
Best regards,
Huan
0 -
-
Hi Maliheh,
Sorry to disturb you again.
I met a new bug for the above mentioned problem.
During the assignment process, and the constraint with respect to v_n can be written as:
W_LP.addConstrs((v[i] == 1 + (4 * z[i] * 10**11)/(W * N_0) for i in range(N)), name="c_linexpr")
the model is infeasible.
However, if the constraint with respect to v_n is written as:
W_LP.addConstrs((v[i] == 1 + (4 * z[i] * 10**8)/(W * N_0) for i in range(N)), name="c_linexpr")
the model is feasible.
Moreover, the full code is shown as follows:
Q = [4200, 3000, 600, 5400, 1700] # each item can be denoted as Q_n
H = [300, 1500, 300, 800, 1100] # each item can be denoted as H_n
M = [200, 300, 120, 300, 200] # each item can be denoted as M_n
M_e = [100, 50, 70, 260, 80] # each item can be denoted as M^e_n
M_l = [100, 250, 50, 40, 120] # each item can be denoted as M^l_n
F_l = [5.5, 3, 7, 8, 10] # each item can be denoted as F^l_n
D = [10, 15, 20, 25, 30] # each item can be denoted as D_n
W = 10000
N_0 = 1

# define the decision variable b_n, which is the integer variable
b = W_LP.addVars(N, lb=0, ub=GRB.INFINITY, vtype=GRB.INTEGER, name="b")

# define the decision variable w_n
w = W_LP.addVars(N, lb=0.1, ub=1, vtype=GRB.CONTINUOUS, name="w")

# define auxiliary variable z_n, so as to add the constraint z_n*w_n=1 and instead 1/w_n with z_n
z = W_LP.addVars(N, vtype=GRB.CONTINUOUS, name="z")

# define the auxiliary variable v_n, which can be used instead of 1+(4*10**11/W*N_0)/w_n in log2(1+(4*10**11/W*N_0)/w_n)
v = W_LP.addVars(N, name="v")

# define the auxiliary variable y_n
y = W_LP.addVars(N, name="y")

# define the auxiliary variable u_n
u = W_LP.addVars(N, vtype=GRB.INTEGER, name="u")

# the objective function
obj = LinExpr(0)
for i in range(N):
   a = Q_t[i] * M[i] - H_t[i] * M_e[i]
   obj.addTerms(a, b[i])
W_LP.setObjective(obj, GRB.MAXIMIZE)

# add the constraint the sum of w_n is 1
constr_1 = LinExpr(0)
for i in range(N):
    constr_1.addTerms(1, w[i])
W_LP.addConstr(constr_1 == 1, name="w1")

# add the constraint z_n*w_n=1
W_LP.addConstrs((z[i] * w[i] == 1 for i in range(N)), name="c2_linear")

# add the constraint v_n=1+(4*10**11/W*N_0)/w_n
W_LP.addConstrs((v[i] == 1 + (4 * z[i] * 10**11)/(W * N_0) for i in range(N)), name="c_linexpr")

# log2(1+(4*10**11/W*N_0)/w_n)
for i in range(N):
    W_LP.addGenConstrLogA(v[i], y[i], 2, name="c_log")

# Model u_i to represent the greatest integer less than y[i] * w[i] * W / D[i]
W_LP.addConstrs((u[i] <= y[i] * w[i] * W / D[i] for i in range(N)))
W_LP.addConstrs((u[i] >= y[i] * w[i] * W / D[i] - 1 for i in range(N)))

# Model b = min(int(F^l_n/M^l_n), u)
for i in range(N):
   W_LP.addGenConstrMin(b[i], [u[i]], int(F_l[i] / M_l[i]), name="b_min")

# set the parameter NonConvex to 2
W_LP.params.NonConvex = 2

W_LP.optimize()
W_LP.computeIIS()
W_LP.write("model.ilp")
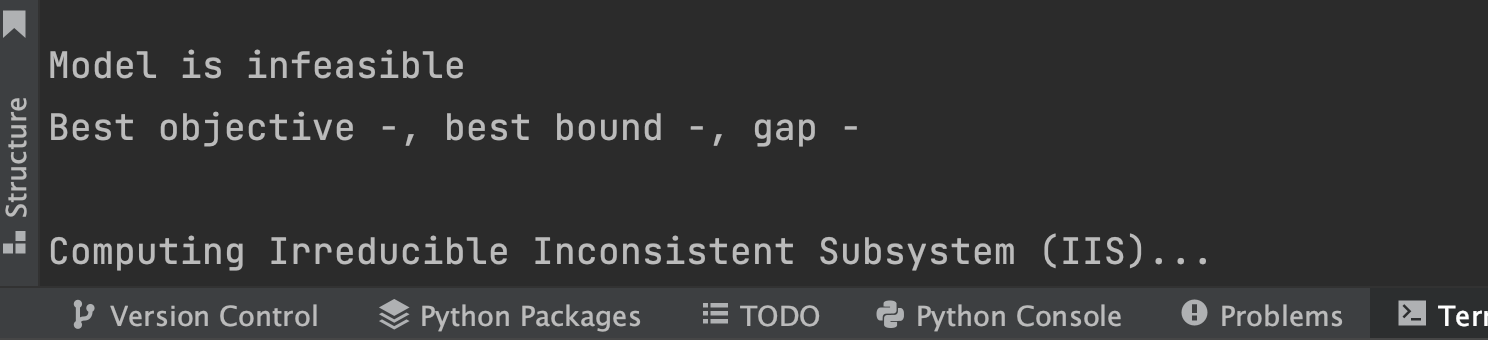
the bug shows that:
the model.ilp file shows that:

Great thanks for your help!
Huan
0 -
-
-
Hi Huan,
I cannot run your code because some of the input parameters such as \(\texttt{N}\), \(\texttt{Q_t}\), and \(\texttt{H_t}\) are not included.
The IIS indicates that if you relax the upper bound of the variables \(w\) to infinity, the IIS sub-system will be feasible.I guess the infeasibility occurs because the bounds of the variables participating in the general function constraints is limited to 1e+6 by default to guard against numerical issues. In your current snippet the variables \(v\) are greater than or equal to \(1+4 \times 10^7\) which is greater than the default value for the FuncMaxVal parameter.
Please post the complete code snippet such that I can run it.Best regards,
Maliheh
0 -
-
Hi Maliheh,
The reason you guessed that the model is not feasible is completely correct.
Based on this, I first reduced the value of v by a certain multiple, and then increased the value of y by the same multiple as y=log2(v).
In this way, the model becomes feasible and I can obtain the optimal solution.
Thank you very much for your help! ^_^
0 -
Post is closed for comments.
Comments
8 comments